Stablecoins in Kenya: stable against what?
The crypto ecosystem glossary distinguishes a monetary reference from a guaranteed price. A token targeting the dollar seeks to maintain a relationship with USD. For a user who pays expenses in KES, its local value also depends on the exchange rate and the price offered by the intermediary.
This distinction changes how performance should be read. A token may remain close to its dollar reference while its shilling equivalent fluctuates. Buying and selling fees can also create a local loss without any dramatic break in the peg.
Before choosing an asset, define the need. Transferring income, paying a supplier and holding a reserve do not require the same timing or risk tolerance. A stablecoin should be assessed across its actual transaction path, not only through a chart showing an almost horizontal line.
Separating the different models
Some stablecoins rely on reserves reportedly held in currencies or financial instruments. Others use crypto collateral and liquidation mechanisms. Algorithmic models seek stability through incentives or supply adjustments. These structures do not carry the same risks.
The term “backed” therefore needs to be explained. What assets serve as reserves? Who holds them? What documents make it possible to assess their status? Who can request a redemption, and under what conditions? A broad marketing statement does not answer these questions.
A token with limited trading activity may also lack liquidity, even if its theoretical mechanism appears clear. Users should examine whether it can be sold and how deep the available bids are. A stated reference does not oblige every counterparty to buy immediately at the same price.
USDT, USDC and issuer documentation
USDT and USDC are among the tokens frequently encountered in crypto services. Their presence in an application does not show that every user has direct access to the same issuance or redemption procedures.
Tether’s legal terms describe the framework for its services. Circle, for its part, publishes information on USDC reserves and transparency. These sources help assess issuer commitments; they do not establish the commercial terms of every Kenyan platform.
Checking the date and scope of each document helps avoid treating an attestation as a universal guarantee. A reserve analysis is not automatically a full audit of every risk. For retail customers, the operational question also concerns the intermediary from which the tokens will be bought, held and later sold.
The shilling price includes the local transaction path
A USDT/KES or USDC/KES quote may include a seller’s margin and payment costs. The USD/KES rate observed in another market is not enough on its own to calculate the amount actually delivered.
In a hypothetical example, two users buy the same quantity of tokens but use different transaction paths. One keeps an internal balance; the other pays a network withdrawal fee. Their final costs therefore do not reflect the same service. Comparing the actual destination helps explain the difference.
Crypto fees in Africa should include the purchase, transfer and exit. A saving at the entry point may disappear after the final conversion. For a business payment, calculating what the recipient receives in usable funds provides more information than the fee advertised for the first step.
Mobile money: do not assume a native conversion
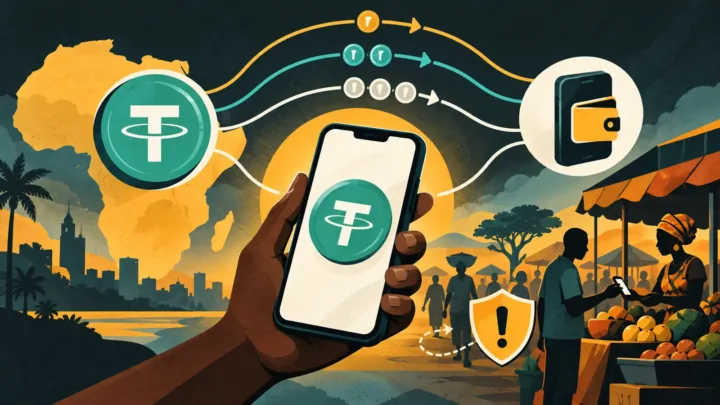
An M-Pesa or Airtel Money account and a stablecoin wallet operate within separate systems. A provider may arrange a transfer between them, but its role must be documented. Mentioning a payment method does not prove an official partnership or a guarantee covering the tokens.
Before paying, identify the monetary recipient and the crypto destination. Check the currency, fees and dispute terms. A debited mobile account does not prove that the tokens were delivered. Conversely, a transfer promise does not demonstrate that payment was received.
The mobile money and cryptocurrency guide helps keep this evidence separate. This discipline is particularly important when selling: a payment message should be checked in the official account before any assets are released under the order’s rules.
Network and token version
A stablecoin may exist on several blockchains. Fees, addresses and confirmation procedures vary by network. The destination must support the exact version selected; the token’s name alone is not enough.
A version obtained through a bridge may add risk linked to that technical intermediary. Readers should understand what they actually hold rather than treating every representation as interchangeable. An identical symbol in a wallet does not prove quality.
Those holding tokens personally should also plan for the fees of the next transfer. Some blockchains require another asset to pay them. Holding only the stablecoin can then make a transaction difficult. Preparing this operational liquidity before a deadline reduces the risk of relying on improvised help at the last moment.
Custody: the custodian adds its own risk
A stablecoin held on a platform depends on access to the account and on the service’s ability to honor withdrawals. The token’s stability does not guarantee the custodian’s solvency. An outage, review or suspension may delay access to the funds.
A personal wallet provides more control but requires proper backup procedures. Losing the keys or authorizing a malicious transaction can cause a loss regardless of the token’s price. Technical security is not just a matter of installing an application.
Comparing solutions therefore requires an assessment of responsibilities. Users should know how to recover access, verify a transaction and arrange legitimate transfer of control. For a business, separating permissions and documenting authorizations prevents one person from moving all the funds without oversight.
Yield and stablecoins: two different decisions
Holding a token that targets a monetary reference does not automatically generate interest. A yield-bearing offer adds a mechanism: lending, investment, liquidity provision or another use of the assets. Each mechanism introduces additional risks.
Ask where the yield comes from and what the withdrawal conditions are before depositing funds. Fixed, high returns deserve particular scrutiny when the business model remains vague. A screen showing gains does not prove that the funds can be recovered.
Recruitment schemes and requests for fees to unlock an account are warning signs. A service may use the name of a well-known stablecoin to give a reassuring appearance to an arrangement unrelated to the issuer. Verifying the actual parties involved helps avoid attributing a third party’s promises to Tether or Circle.
Regulation and professional use in Kenya
The regulatory framework published by the CMA organizes the activities of service providers. The existence of these texts does not automatically validate every stablecoin offer accessible from the country. Checking the entity and the service remains necessary.
For professional compensation, specify the contract, the reference currency and the timing of conversion. A price billed in dollars differs from a fixed quantity of tokens. The risks and fees should be clearly allocated between the parties.
Keeping invoices, the value used and transaction references enables accounting follow-up. Payment on a blockchain does not remove the nature of the income or the relevant obligations. Regular commercial activity warrants an appropriate analysis, particularly when it involves several countries or funds held for clients.
A spending reserve is not managed like a transfer
A short transfer exposes funds for a limited period, while a reserve holds them over time. Custody, recovery and conversion risks therefore become more significant. A tool suited to sending income is not automatically suitable for every future expense.
Separating amounts needed in the short term from funds intended for digital use can reduce this dependence. For a professional, this separation also makes it easier to track clients and suppliers. The choice should remain tied to actual deadlines and the ability to recover shillings, not only to the stability displayed against the dollar.
Preparing for difficult scenarios
A break in the peg, a withdrawal suspension or a shortage of counterparties can disrupt a planned payment. Defining an alternative procedure in advance helps avoid a forced sale. The alternative must remain legitimate and documented, rather than relying on borrowed accounts.
In a hypothetical case, a company must settle an invoice in KES while its crypto provider has suspended withdrawals. The problem may concern the custodian rather than the token. Distinguishing between these causes makes it possible to choose an appropriate response instead of blindly moving funds to another unknown platform.
Stablecoins in Kenya offer a reference and transfer tool, not absolute protection. Their usefulness depends on the network, custody arrangements and conversion options actually available. A sound decision considers the final amount usable in shillings, proof of delivery and the consequences of an incident before entrusting funds to the chosen transaction path.