Ordinance No. 2024-56 of December 19, 2024, includes provisions for virtual asset service providers, or VASPs. This guide offers a control framework for entrepreneurs, partners and professional clients. It does not replace advice from a Nigerien counsel and does not provide a compliance certificate for any specific business.
In brief
- The actual scope of the service matters more than labels such as “technology” or “intermediary.”
- Authorizations and responsibilities must correspond to each entity in the chain.
- Compliance must be documented before launch and reviewed whenever the business changes.
Crypto regulation in Niger: mapping the actual business activity
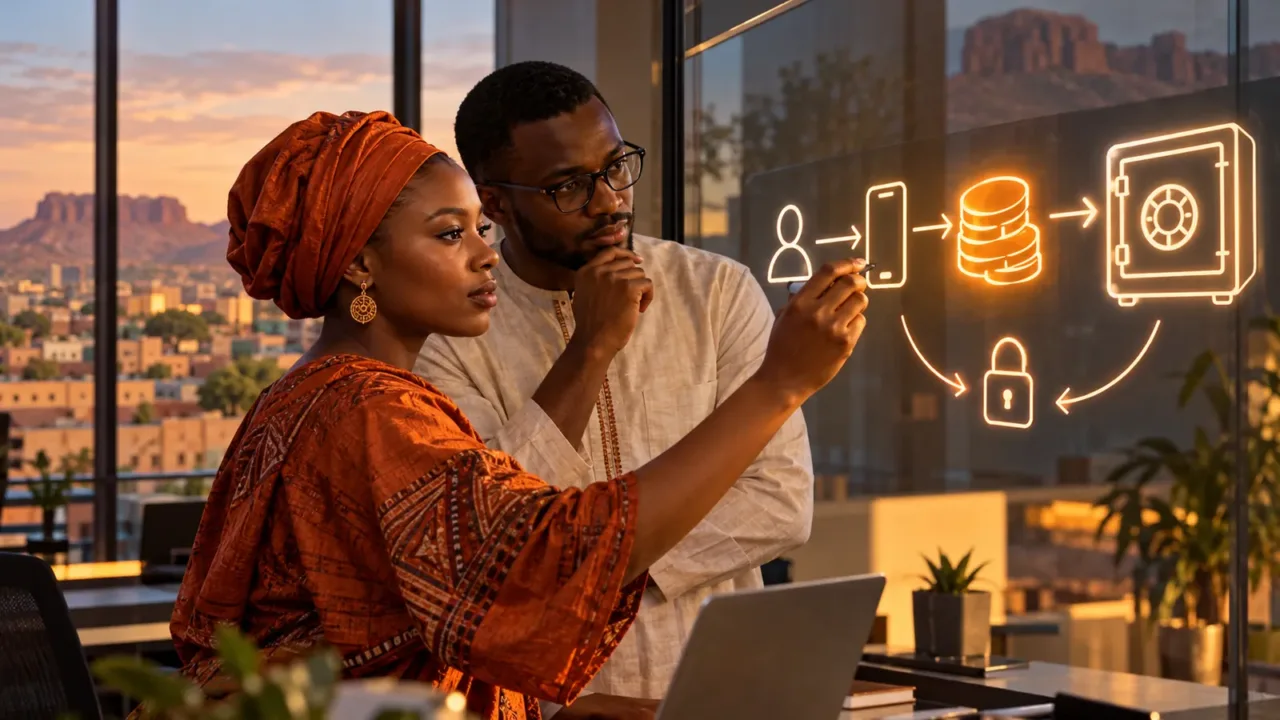
The UEMOA and crypto overview provides an initial regional framework. For a Nigerien project, however, start by mapping the flows: the origin of XOF, the payment recipient, the asset seller, the place of custody and the client’s exit route. Each arrow should identify an entity and a contract. A single interface may conceal several distinct relationships.
Then describe each participant’s powers. Who can move assets without a new client instruction? Who sets the price, receives commissions, controls withdrawals and handles complaints? These questions help distinguish a tool provider from an operator that actually takes responsibility for third-party funds or keys.
Partners must meet the same standards of precision. A payment operator may accept CFA francs without handling crypto delivery. A hosting provider may supply the interface without holding the assets. Do not treat one link’s authorization or reputation as proof covering the entire chain; examine each party’s specific commitments.
A written inventory also helps identify cross-border situations. Record the seller’s country of establishment, the clients’ countries and the locations where conversions take place. A service accessible from Niamey does not necessarily fall under a single legal system. A French translation of the contract, by itself, says nothing about the applicable jurisdiction or the remedies available.
Finally, distinguish personal use from providing services to others. The crypto wallet guide explains the technical aspects of key control. For a professional project, that capability must also appear in the legal analysis. Assistance that secretly retains clients’ recovery methods goes beyond simple training.
Read the ordinance and document the points that still need confirmation
The Nigerien CENTIF lists national legislation, including Ordinance No. 2024-56. Articles 58 and 59, shown on page 41 of the document, address the professional operation of VASPs and anti-money-laundering, counter-terrorist-financing and counter-proliferation requirements. This material should be included in the file for any affected project.
The provision on prior authorization should not be treated as a commercial detail. Ask counsel to classify the activity, identify the competent authority and specify the steps required before launch. We have not verified an exhaustive list of VASP licenses issued in Niger or all implementing texts currently in force here; no business therefore receives a compliance label based on this reading alone.
Incomplete research does not prove that an obligation does not exist. It means that a point must be confirmed through a document or a competent response. Keep a register of open questions covering the authority, procedure, scope, deadlines, control requirements and reporting obligations. Assign each question an owner and an expected form of evidence rather than assuming a favorable answer.
Do not automatically transpose a foreign regime. A registration obtained elsewhere may concern a different entity, service or customer base. Likewise, Nigerian rules do not apply in Niger simply because the countries’ names are similar. The sound analysis connects the national text, the proposed service and the situation of the people actually concerned.
For a project already in operation, the review should begin with actual practices, including informal procedures. A transfer carried out manually by an employee or a payment received into a personal account belongs in the risk map. Do not limit the review to the features described in a commercial presentation if clients use a different process in their daily transactions.
Verify the contracting entity and its payment partners
The crypto platform comparison framework offers questions that apply to professional partnerships: which legal entity signs, in which jurisdiction, for what service and with what liability? Obtain these answers before technical integration. A successful demonstration does not make up for the absence of a contract defining the entrusted funds and the obligations to return them.
Review payment services separately. The BCEAO publishes electronic money institutions and their partnerships. Such a list verifies a specific status; it does not validate the crypto activity of every distributor or customer using the service. A commercial agreement should specify exactly what the partner authorizes within the contemplated flow.
Ask how client funds circulate and how they are separated from the company’s own resources. Who reconciles the payment with the delivery? What happens if an order fails after the debit? Which entity keeps the evidence and decides whether to issue a refund? These operational questions require contractual answers, without promising protection that the arrangement does not provide.
Commercial limits should also appear in client information: eligible residence, required documents, payment methods, minimum amounts, fees and any restrictions. The guide to buying crypto with Mobile Money shows why the failure of a single link can leave a transaction stuck. A service should not market an “instant” experience without explaining the checks that may interrupt it.
Document changes to partners and the addition of subcontractors. A new provider may change the processing country, data access or withdrawal terms. An approval procedure helps prevent a limited technical decision from silently changing the legal profile of the entire product. Clients should be informed of developments affecting their rights under the applicable rules.
Organize controls without turning KYC into indiscriminate data collection
A compliance framework begins with proportionate, approved procedures, not with a blanket request for every possible document. The KYC and data overview helps frame questions about purpose, security and remedies. Have the specific obligations for the activity and the people concerned confirmed before finalizing your forms.
Controls must connect the declared identity with the transactions carried out. A name mismatch, funds originating from a third party or activity different from what was declared requires a documented procedure. Employees should not improvise decisions alone under pressure from a client or sales target. Set approval levels and keep a record of decisions.
Data protection requires restricting access and securing transmissions. Never request a recovery phrase or Mobile Money secret code to verify someone’s identity. These secrets grant transaction power; they are not reasonable proof of compliance. Support teams must understand this boundary so they do not reproduce fraudsters’ methods.
Have competent personnel establish the rules for retention, updating and alert handling. This guide does not set a uniform period applicable to every document or a universal reporting threshold. The rules depend on the text, status and circumstances; publishing an unverified figure would create more confusion than clearly leaving the question open for confirmation.
Effective controls also cover failure scenarios: an unreadable document, a compromised account, a disputed payment, a suspended withdrawal or a deceased client. Each scenario should specify the relevant evidence and authorized contacts. The aim is neither to accept everything nor to block everything, but to make decisions understandable, defensible and consistent with the applicable obligations.
Test incidents, exit procedures and client communications
Before going live, test an end-to-end transaction within an authorized framework and using an appropriate amount. Check the quote, payment, credit, withdrawal and exportable records. A technical test does not establish legal compliance; it allows you to compare actual operations with the commitments approved in the file.
The full-cost calculation should accompany these tests. A displayed commission may exclude conversion costs, partner fees or the final withdrawal. Explain what the client pays and what they actually receive. Clear billing reduces disputes and prevents a market movement from being confused with a charge imposed by the service.
Then simulate an incident without exposing a real client’s funds. What does the user see if the payment succeeds but the credit is pending? Can they find a unique reference? Does support distinguish a payment problem from a blockchain issue? A journey that hides these states behind a generic message increases duplicate payments and conflicting requests.
Marketing communications must remain consistent with the available evidence. Do not promise general validation by an authority, guaranteed reimbursement or risk-free returns if no verified mechanism supports those claims. Terms such as “secure,” “licensed” and “partner” must refer to an identifiable scope. A disclaimer in fine print does not correct a misleading central promise.
Finally, schedule regular reviews of the file and additional reviews after any significant change. Launch does not end compliance work: new assets, a different customer base, outsourced custody or another payment channel may alter the analysis. In Niger, a sustainable approach means keeping evidence up to date and suspending functions whose conditions can no longer be demonstrated, rather than relying on an outdated reassuring presentation.