Building crypto income without leverage in 2027 will involve more than simply switching off a borrowing function. It will also require reviewing the underlying operations, separating income from capital sales and planning an exit. Avoiding debt reduces certain constraints, but it does not guarantee the value of the assets or the outcome of a contract.
This guide offers an organizational framework, with no personalized allocation or income guarantee. Primary sources were consulted on November 9, 2026; parameters and access conditions will need to be checked again in 2027. The simulations are fictional and illustrate the limits of an income target, not an expected performance.
In brief
Our guide to a €500 crypto portfolio helps define available capital before searching for a rate. An income plan must then specify what it can afford to lose, what must remain available and which obligations it refuses to take on.
- Here, no leverage means not financing exposure with debt, either directly or through the chosen strategy.
- Token rewards do not guarantee stable income in the currency used for expenses.
- A complete method accounts for fees, shared dependencies and exit conditions before funds are deposited.
Set the objective before choosing a mechanism
A target of €100 per month may appear modest, but it requires substantial capital if the assumed net income remains low. The amount should not be derived from a temporary promotional rate. The currency, desired regularity, time horizon and level of capital loss that could genuinely be tolerated must be defined first.
In a fictional calculation, generating €1,200 per year at a constant net return of 3% requires €40,000 in capital. At 6%, the theoretical amount falls to €20,000. These assumptions do not describe any specific offer and do not ensure that income will be available every month. They simply show why the denominator matters.
A strategy should not fund essential expenses with unguaranteed income without acknowledging that fragility. A reserve for near-term needs and capital committed to a risky activity serve different purposes. Keeping them separate helps avoid forced selling merely to meet a spending schedule.
Investor.gov’s overview of asset allocation highlights the role of time horizon and loss tolerance. These principles do not provide a universal crypto allocation. They help establish constraints before comparing products and recognize that the same objective will not suit everyone.
Check that the strategy is debt-free from end to end
A position may be opened without personal borrowing while representing a vault that uses loans or repeated internal transactions. The analysis must therefore examine the mechanisms themselves. Simply not clicking “borrow” does not prove that the exposure is free of debt.
Our guide to crypto lending helps distinguish between a provider and a borrower. Supplying an asset to a market does not necessarily mean taking on personal debt. However, the strategy still carries credit, smart-contract and liquidity risks that do not disappear merely because the depositor is not using leverage.
Representative assets must also be examined. A token may provide access to a strategy that is more complex than its apparent form of ownership. Rights, operations and redemption constraints should be documented. If the user cannot establish what happens beneath this layer, they cannot honestly claim to understand the exposure.
Yearn’s documentation on strategy risks notes that products inherit their underlying dependencies. This does not condemn all automation; it prevents a simplified interface from being treated as proof of simplified risk. The analysis must follow the capital’s actual path.
Choose an income source you can explain
Staking rewards a function linked to consensus under a network’s rules. Lending rewards making assets available to a credit mechanism. A liquidity position may earn trading fees. These sources involve different commitments and should not be added together without examining the assets exposed.
The guide to staking and validation risks covers the first category. A network reward is not a coupon paid in the currency used for spending. Operator fees and changes in the token’s price further affect the result.
A framework can retain one understandable primary source and examine another only if necessary. Multiplying mechanisms before learning how to monitor them increases the number of assumptions. Seeking income does not require participating in every innovation or choosing the most complex products to reach a target.
Temporary incentives should remain a separate line item. A plan can calculate the result with and without them. If the target is reached only by assuming that the incentives continue and the sale value remains unchanged, that dependence should be stated explicitly. A campaign does not become an annuity simply because it distributes rewards regularly.
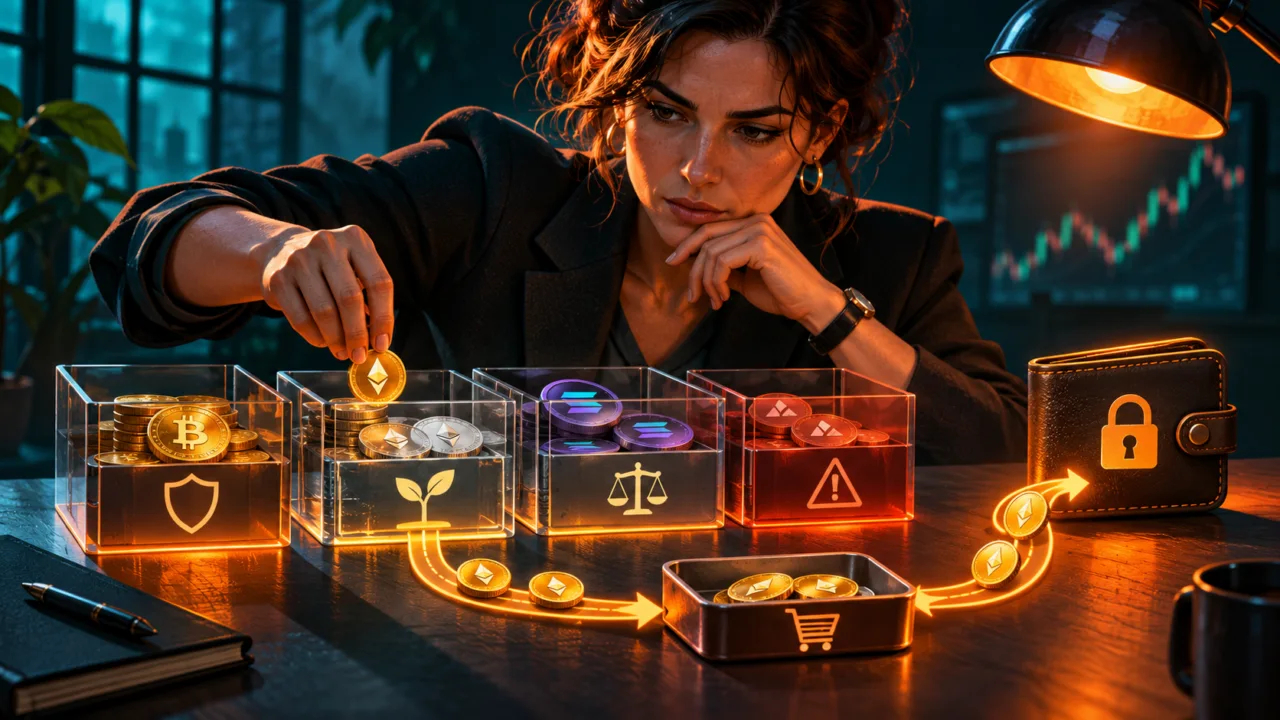
Build compartments that do not all share the same failure point
Multiple positions do not automatically create meaningful diversification. They may depend on the same stablecoin, oracle, bridge or common service provider. The table should therefore map these dependencies instead of merely counting the number of logos in the portfolio.
An operating reserve funds transactions and exits. It must be distinguished from assets already committed. If all the capital is held in a mechanism that could block withdrawals, the “reserve” line does not represent demonstrated availability. The reader must identify where the funds can be used and in which currency.
A second compartment may consist of capital whose risk is accepted and documented. Amounts should not be chosen based on a rate promise; they should follow loss capacity and concentration. This method does not guarantee that no harm will occur. It prevents yield alone from determining exposure.
European authorities note in their warning on crypto-assets that protections and risks depend on the assets and services used. Checking whether a provider is authorized under the applicable framework remains useful, but its status should not be confused with insurance against a market loss.
Calculate net income, capital changes and withdrawals separately
A fictional simulation can start with 10,000 units committed and gross annual income of 500. After 100 in fees, 400 remains before tax. Withdrawing 100 each month, or 1,200 over the year, would then require 800 additional units to be taken from capital if no other income is generated. Regular payments do not create the missing income.
Asset valuation must be tracked separately. If a position gains 4% in units but their price falls by 20%, its theoretical final value equals 83.2% of the initial value, excluding other flows. Positive income is therefore not enough to claim that savings are protected or purchasing power preserved.
The guide to crypto fees helps incorporate the costs of the full process. An APY net of manager fees may still be gross of the user’s own transaction costs. The frequency of withdrawals should be consistent with the amount received and the conditions, rather than selected solely to display daily income.
A monthly report can separate personal contributions, accumulated income, collected income, expenses, capital withdrawals and remaining value. This structure makes it possible to acknowledge a disappointing result without redefining success after the fact. It also helps retain supporting documents for applicable tax purposes, without assuming a universal treatment.
Define reduction and exit conditions
A complete method records the changes that would trigger a fresh analysis: a strategy modification, a contract incident, an asset losing its peg or a deterioration in liquidity. The aim is not to predict every problem, but to avoid making “continue as long as the interface shows a positive rate” the only rule.
The exit should be described step by step, including the asset returned, network, costs and conversion stages. A limited test can verify that the process is understood without guaranteeing the same future conditions. A secondary market and an underlying redemption should not be treated as one promise of permanent liquidity.
Self-custody wallets help users control signing methods. A backup and a clear understanding of access matter just as much when exiting as when entering. No support agent should ever receive a seed phrase to speed up a withdrawal or unlock allegedly withheld rewards.
The strategy can also decide not to reinvest automatically. Reducing exposure or keeping income available may better meet spending needs than permanent compounding. The choice should be explicit and included in the calculation, rather than presented as a mistake because it lowers a theoretical return.
For 2027, building crypto income without leverage therefore means removing debt from the financing structure without overlooking everything else: assets, contracts, custody, liquidity, costs and currency exposure. A sound plan explains where the income comes from, what can be lost and how to exit. When an answer is missing, adding capital does not resolve uncertainty about the mechanism.